If you have heard terms such as Bitcoin, Web3, smart contracts, or digital assets, you have probably encountered blockchain technology. But what is blockchain technology, and why does it matter beyond cryptocurrency?
In simple terms, a blockchain is a shared digital record that stores information across a network of computers. Instead of relying on one central database, many blockchain systems distribute copies of the record among participating computers.
Blockchain has applications beyond digital currencies. It can be used for payments, supply-chain tracking, digital identity, healthcare information, financial services, and digital ownership. Understanding the basic idea is therefore useful for students, business owners, technology enthusiasts, and anyone interested in how modern digital systems are evolving.
What Is Blockchain Technology?
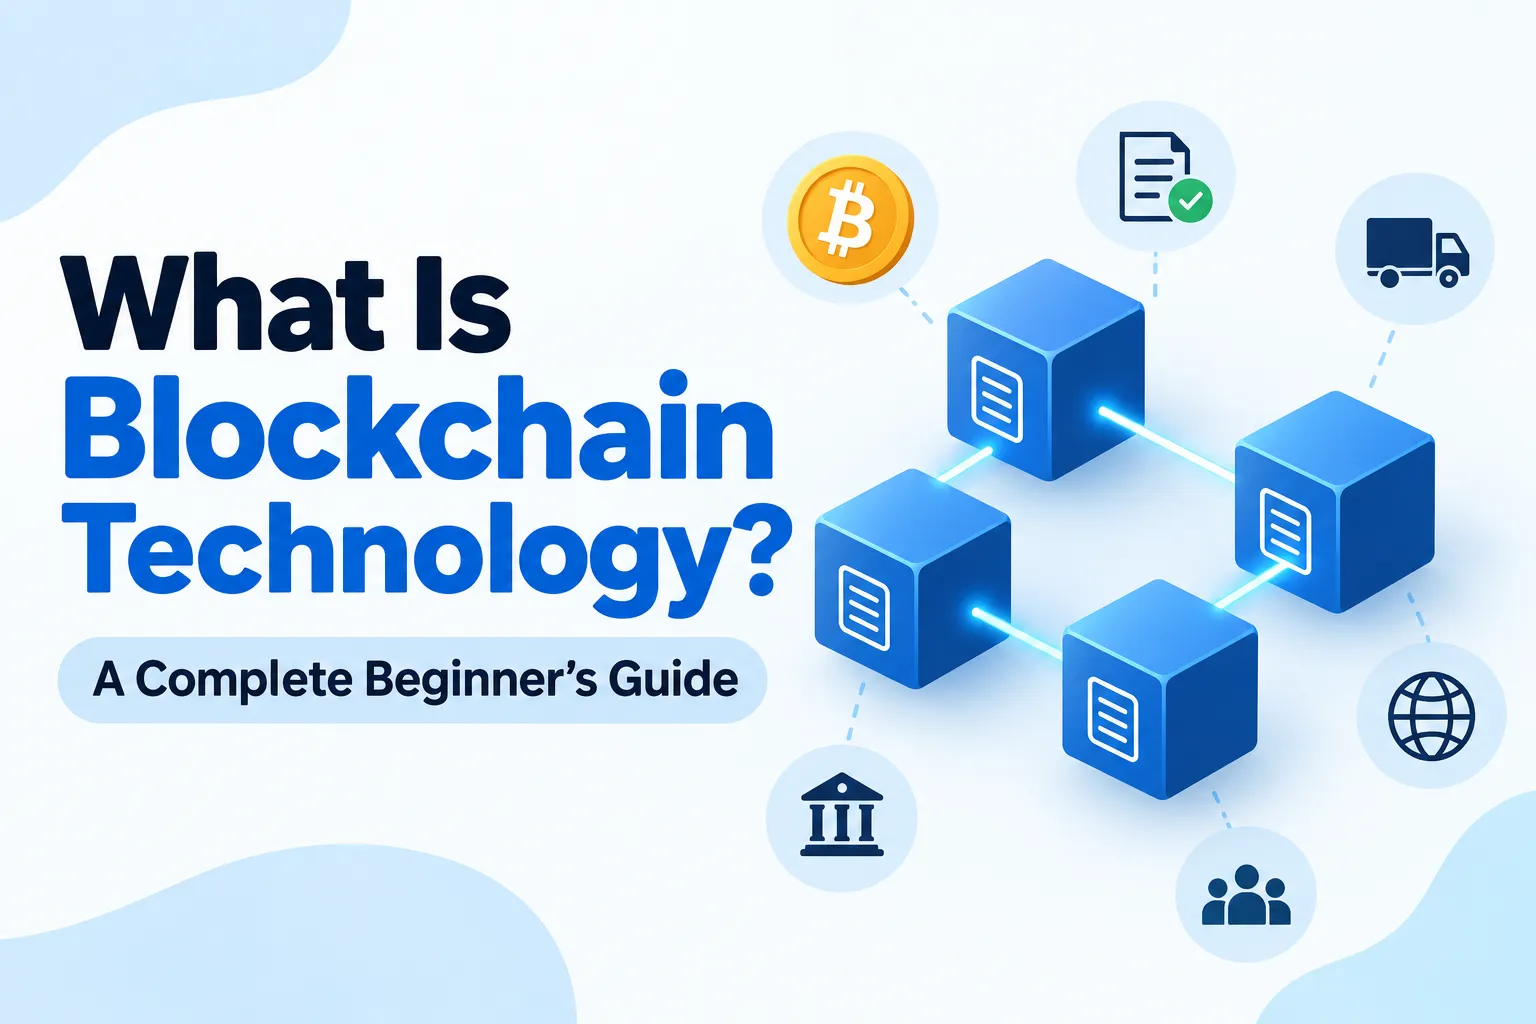
Blockchain technology is a type of distributed digital ledger that records transactions or other information in linked groups called blocks.
Think of a blockchain as a shared digital record book. Imagine several people keeping identical copies of the same notebook. When a new entry is made, the group checks it according to agreed rules. Once accepted, the entry becomes part of the shared record.
A blockchain uses similar principles digitally.
- Digital ledger: A record of transactions or other information.
- Block: A group of verified records stored together.
- Transaction: An exchange or recorded event, such as transferring digital currency.
- Network: The computers and participants that maintain or verify the blockchain.
- Decentralization: Control and record keeping are distributed among multiple participants rather than relying entirely on one central authority.
Blocks are connected using cryptographic references, helping make previously recorded information difficult to alter without detection. The exact design varies between blockchain networks.
How Does Blockchain Work?
Although blockchain systems can be technically complex, the basic process can be understood in six steps:
- A transaction or piece of data is created.
For example, someone initiates a digital payment. - The information is broadcast to the network.
Participating computers receive the proposed transaction. - Network participants verify it.
The network uses predefined rules and a consensus mechanism to determine whether the transaction is valid. - Verified transactions are grouped into a block.
Multiple accepted records can be packaged together. - The block is added to the blockchain.
It is linked to earlier blocks using cryptographic references. - The updated record is distributed across the network.
Participating computers update their copies according to the network’s rules.
The exact process differs between blockchains. For example, Bitcoin and Ethereum use different technical mechanisms and have different network designs.
What Is a Block in Blockchain?
A block is a container for a group of recorded transactions or other data.
A typical block can include:
- Transaction data: Information about the transactions or records being stored.
- Timestamp: Information indicating when the block was created or recorded.
- Previous block reference/hash: A cryptographic reference connecting the block to the preceding block.
- Current block hash: A value associated with the block’s contents.
This linking creates a chronological chain of blocks. If someone attempts to modify previously recorded information, the cryptographic relationships can no longer match as expected, making unauthorized changes easier for the network to detect.
What Makes Blockchain Different From a Traditional Database?
Blockchain is not automatically better than a conventional database. The right technology depends on the problem being solved.
| Feature | Traditional Database | Blockchain |
| Control | Usually centralized | Often distributed |
| Data management | Controlled by an administrator | Shared across a network |
| Data changes | Can usually be edited | Recorded data is designed to be tamper-resistant |
| Transparency | Depends on access permissions | Can provide shared visibility depending on design |
| Use cases | General data storage | Shared records and transactions |
A traditional database can be faster, simpler, and more efficient for many applications. Blockchain becomes more interesting when multiple parties need to share records without relying entirely on one organization to maintain the authoritative copy.
Key Features of Blockchain
Decentralization
Decentralization means control or record keeping can be distributed among multiple network participants. The degree of decentralization varies significantly between blockchain systems.
Transparency
Some blockchains allow participants to inspect transaction records. However, transparency does not necessarily mean that users’ real-world identities are publicly visible.
Immutability and Tamper Resistance
Blockchain records are designed to be difficult to change after confirmation. It is more accurate to describe this as tamper resistance rather than saying blockchain data is absolutely impossible to change.
Security
Cryptography, network verification, and distributed record keeping can help protect blockchain records. Security ultimately depends on the particular network and its implementation.
Traceability
Because transactions can be linked into a historical record, blockchain can provide an auditable trail that helps organizations track recorded events.
Types of Blockchain
Public Blockchain
A public blockchain is generally open for broad participation. Bitcoin and Ethereum are well-known examples. Their records can be publicly inspected, although the exact visibility and participation rules differ.
Private Blockchain
A private blockchain restricts participation to authorized users. An organization might use one when it wants distributed record keeping while maintaining tighter control over who can access or validate information.
Consortium Blockchain
A consortium blockchain is operated by multiple organizations that jointly participate in maintaining the network. This model can be relevant when several businesses need to coordinate shared records.
These categories can overlap, and blockchain designs vary considerably.
What Is Blockchain Used For?
Blockchain applications extend beyond cryptocurrency.
- Cryptocurrency and payments: Networks such as Bitcoin record transfers of digital currency.
- Supply chains: Companies can use blockchain-based systems to record events as products move through different stages.
- Digital identity: Blockchain may support systems for managing or verifying certain identity-related credentials.
- Healthcare: Blockchain can potentially support controlled sharing and auditing of specific healthcare-related information, although privacy and regulatory requirements are significant.
- Smart contracts: Programs on compatible blockchains can automatically execute predefined actions.
- Financial services: Blockchain-based systems can support settlement, tokenized assets, and other financial infrastructure.
- Digital ownership and assets: Blockchain can record ownership or transfer information for certain digital assets.
- Business records: Multiple organizations can use shared ledgers to coordinate records and transactions.
Blockchain and Cryptocurrency: Are They the Same?
No.
Blockchain is the underlying technology, while cryptocurrency is one application of that technology.
Bitcoin is a cryptocurrency that operates on the Bitcoin blockchain. However, blockchain systems can be designed for purposes other than digital currency, including business records, asset tokenization, and automated applications.
Likewise, different blockchain projects can have very different architectures, governance models, and purposes.
What Are Smart Contracts?
A smart contract is a program stored and executed on a blockchain that can automatically perform actions when predefined conditions are satisfied.
For example, imagine an agreement stating: “If condition A occurs, transfer asset B.” A smart contract can be programmed to execute that rule automatically when the required conditions are met.
Smart contracts are commonly associated with decentralized finance, digital assets, decentralized applications, and automated business processes. However, they can contain programming errors, so automation does not automatically make an application safe.
Advantages of Blockchain Technology
Depending on the design and use case, potential benefits include:
- Shared record keeping across multiple participants
- Greater transparency in suitable systems
- Tamper resistance
- Traceable transaction histories
- Reduced dependence on intermediaries in some processes
- Automation through smart contracts
These benefits should not be treated as universal. A blockchain may introduce costs and technical complications that outweigh its advantages for a particular application.
Limitations and Challenges of Blockchain
Blockchain technology also has important limitations.
- Scalability: Some networks have difficulty processing large volumes of transactions efficiently.
- Energy consumption: Certain consensus mechanisms, particularly proof-of-work, can require substantial energy.
- Transaction speed: Confirmation times vary and may be slower than centralized systems.
- Storage requirements: Distributed networks may require participants to store significant amounts of data.
- Regulatory uncertainty: Rules surrounding blockchain applications vary by jurisdiction and use case.
- Privacy challenges: Publicly recorded data can create privacy concerns if systems are poorly designed.
- Implementation complexity: Developing and maintaining blockchain systems requires specialized expertise.
- Cost: Network fees, infrastructure, development, and operational expenses can be significant.
Is Blockchain Technology Secure?
Blockchain can provide strong security properties, but it is not automatically secure in every situation.
Cryptography helps protect data and authenticate transactions. Consensus mechanisms help network participants agree on which transactions should be accepted. Distributed record keeping can make unauthorized changes more difficult.
Users also have responsibilities. For example, losing a private key can mean losing access to assets controlled by that key.
Other risks include:
- Stolen private keys
- Smart contract vulnerabilities
- Phishing attacks
- Poorly designed applications
- Weak security practices around wallets or accounts
Therefore, blockchain-level security and application-level security are not the same thing.
What Is the Future of Blockchain Technology?
The future of blockchain technology is likely to involve a mixture of experimentation, specialized applications, and integration with existing technology.
Potential areas include digital identity, tokenization, supply-chain management, financial infrastructure, decentralized applications, and business record systems. Blockchain may also increasingly interact with technologies such as cloud computing, artificial intelligence, and Internet-of-Things systems.
These are potential developments rather than guarantees. Adoption will depend on factors such as cost, regulation, usability, performance, privacy, and whether blockchain provides a meaningful advantage over existing technologies.
Frequently Asked Questions
1. What is blockchain technology in simple words?
Blockchain is a shared digital record system that stores information in linked blocks across a network. Its design can make recorded information difficult to alter without detection.
2. How does blockchain work?
A transaction is created, shared with the network, verified according to network rules, grouped into a block, and linked to previous blocks before participating systems update their records.
3. Is blockchain the same as Bitcoin?
No. Bitcoin is a cryptocurrency that uses blockchain technology. Blockchain itself is a broader technology with applications beyond cryptocurrency.
4. What are the main benefits of blockchain?
Potential benefits include shared record keeping, transparency, tamper resistance, traceability, and automation in suitable use cases.
5. Is blockchain technology secure?
Blockchain can provide strong security mechanisms, but applications can still be compromised through stolen keys, coding vulnerabilities, phishing, or poor implementation.
Conclusion
Blockchain is best understood as a technology for recording and sharing information across a network. Instead of relying entirely on one central database, many blockchain systems distribute records among multiple participants and use cryptography and consensus mechanisms to maintain their integrity.
You do not need advanced programming or cryptography knowledge to understand the fundamentals. Once the basic concepts are clear, topics such as cryptocurrency, Web3, decentralized applications, tokenization, and smart contracts become much easier to explore.
The key is to view blockchain as a technology rather than as a synonym for cryptocurrency. Like any technology, its value depends on how—and where—it is designed and used.